Best Health Insurance
To see the best health insurance plans, start by providing a few details about yourself:
RT Health Insurance 🏆 2026
4.9Award Winning, Affordable, Not-For-Profit Health Insurance.

Teachers Health Fund 🏆 2026

- See all


I’m so glad we have signed up to Teachers Health, the plans are easy to compare and they cover so much more the other health insurance companies.… Read more
Jonathan from Teachers Health was absolutely amazing he explained in detail all of the policies, which made it easy to work out the best cover for our needs.
RT Health 🏆 2026


- See all

Great customer service from Anna, she was one of a kind!! Show details

AIA Health Insurance 🏆 2026

- See all


Terrible company - the app never works - and they never answer the phone. Go with BUPA. Show details

Phoenix Health Fund
Adam called back at a time that suited me and was very clear and knowledgeable Show details

Queensland Country Health Fund
Queensland Country Health is a brilliant private health insurance provider. I have been with them since 2009 and their responsiveness, efficiency and claims process has always been exceptional. Show details

see-u by HBF
Lucy was absolutely amazing and knows her health insurance stuff. Lucy has potentially saved me thousands of dollars. Thank you Lucy. Show details

Westfund Health Insurance
I have been a member of Westfund Health Fund for a few years and I have always found them so easy to contact by phone, answered by an english… Read more
speaking person and no extensive waiting time. Lodging a claim online is a breeze and their service is great. Recently I received an email from them informing me they were waiving the $500 excess for same day surgery up until 31st December 2026. I was booked for day surgery within the following week, so I was delighted not to have to pay the excess. Westfund, a not-for-profit Fund, is conducting a Giveback for Good Health package during 2026 which includes a variety of more back on everyday health. I just want to spread the cheer.

Australian Unity Health Insurance
- See all


good until there not.. I've been. With Australian unity since 2009. In that time, I've always had my non PBS GP prescribed Medication covered under… Read more
my pharmacy On my extras. There was a few occasions where they didn't cover my pharmacy once I submitted my receipt. But I spoke to a supervisor and they back paid me for the Times, they did not pay me. They assured me that moving forward my pharmacy would still be covered as my medication is not on the PBS. Well, you can imagine my surprise when they stopped covering my pharmacy again. I was put in touch with someone from a different department and he said to me m y medication Is not covered because it's not FDA approved. I questioned how it's not FDA approved If a GP Is prescribing it. He said to me that my life saving Prescribed medication is nothing more Then supplements. I said to him they're not supplements, they're GP prescribed Through a compounding pharmacy. If they were supplements, I would be able to order them over the counter or online. I asked to speak to a supervisor and explain to him that I was assured my medication would be covered. He said to me there's no one higher than me. I'm the last stop. And we're not covering your medication moving forward.
My medication costs a few dollars every five weeks and whilst some small amount Is a great help I have to budget as cost of living you can imagine is quite expensive. So that additional amount that they're not covering now? Has put a strain on my finances. And I have had to reduce my medication dosage and in result have not been feeling great because I haven't been able to afford the medication.
To the person who denied my medication may you get the same karma back for a family member. Australian Unity. You can kick rocks.
No doubt I will have a generic templated response."" Let's talk about it Please touch base""". I've done all that Australian unity. I've touched base. I was refused to speak to a supervisor because The person that denied my medication apparently is The top tier person higher than the CEO higher than any supervisor in the company, and apparently there was no one else to talk to. So yes, you can kick rocks. Both the company and your templated response.

Hi there, thank you for sharing your feedback.… Read more

Allianz Care
- See all


I had a referral from my GP to do endoscopy procedure. I discussed it with the representative, Kiyomi at Griffith Nathan, and she gave me some… Read more
suggestions since it was my first experience. She was helpful and provided me with hands-on information and direction to obtain eligibility form, as well as to communicate with my GP and the hospital. A week before the procedure, she told me to contact and follow up my eligibility submission by providing medicare benefits schedule item number from the hospital. Less than an hour, I got Guarantee of Payment OSHC policy for the procedure. I have my endoscopy procedure covered by my OSHC, so I did not need to pay anything. Thank you Allianz. It is so easy to have my procedure at the hospital covered by OSHC.

TUH Health Fund
- See all


My wife and I have been with tuh for well over 10 years and been given the very best service the entire time Very prompt and courteous at all times Show details

Nurses & Midwives Health

- See all


Semina was incredibly helpful with all the information available and not pushy! Show details

Peoplecare Health Insurance
I joined peoplecare 1 year ago and needing to have a hospital operation made my first claim. This has been rejected with the reason being I hadn’t… Read more
given them my account details. I received an email saying they had tried to contact me and has they had been unsuccessful they had rejected my claim. They can send me an email to reject my claim however I have not received any emails asking me to submit my account details. I also have no phone messages so I’m not sure what their unsuccessful attempts to contact me are. Not great peoplecare.

Hi Paul, we're sorry to hear about… Read more

Frank Health Insurance
I live in a rural area with no mobile phone coverage. Frank then decides that because I have no mobile coverage I should no longer have access to my account details online. If you abuse me I don't deal with you. Show details

GMHBA Health Insurance
- See all


Absolute nonsense! As if I know what a clearance certificate is? Went to these guys through one of those compare services and the entire family was… Read more
put on 12 months wait. Now my wife and I can claim but not the kids. Looking to cancel now, you know what? Freedom to just do what we like when we like feels pretty fun. No more trying to wring value out of $1000/year. Bye bye!

ItsMy Health Insurance
The customer service from Shannon was amazing and very helpful I would highly recommend. Show details

Police Health
- See all


I was in Police Health back in the 1990's but a marriage change and I was in BUPA for 20 years but now have rejoined and I'm extremely happy with their policy and service and very happy to be back. Show details

ahm Health Insurance

- See all


Today 10 September, Jordan resolved my issue immediately with proactive actions. His thoroughness in analysing the situation and fixed the issue had… Read more
earned the recognition of an excellent performer!
His "follow up" attitude and patience also are his strengths in servicing his clients!

Defence Health Health Insurance
When I needed them most for upcoming surgery to remove invasive cancer, Defence Health abandoned me offering to only cover 5% of the specialists… Read more
fees. Their solution was to effectively shop around my surgery to the lowest possible bidder! Think I'll stick with the specialist I have had monitoring the condition for the last 5 years. So disappointing.

Rick, we're sorry to hear about the out-of-pocket… Read more

HBF Health Insurance

- See all


Ive been with hbf for over a decade. Service was good years back. Not anymore. Show details

Hi Dan, I'm sorry to hear you have had a bad experience with… Read more (+1 reply)

Health Partners
I have only just joined Health Partners having had problems with making claims and adjusting my membership digitally with another fund. It was… Read more
such a relief to get friendly and professional assistance during the joining process so looking forward to a hassle free membership with a local fund.

Doctors' Health Fund
This company is a disgrace. I have been a member now for many years and I am paying nearly $10,000 a year in premiums. I rarely make claims but… Read more
recently I had a hospital admission and submitted my claims soon after. These people give me the runaround constantly. They blame Medicare, Medicare blames them and then they both blame the provider and the only person that suffers me. I’ve spent over two hours on the phone with them in the past week and each time someone has given me a different answer or reason to why my claim is being held up. They make dreadful errors at my expense and when you email them to try to find out what’s going on, they either ignore you or respond with a single line and you are no better informed than you were previously. I will be getting out of this health fund as soon as I possibly can. Please think very carefully before joining them because if you need to make a claim, they will not pay it and they will make mistake after mistake and you will be chasing your tail for months on end until you finally give up because they wear you down. I outlaid $36,900 for a procedure and so far I have received $900 back. I pay top hospital cover. That is an absolute disgrace.

HCF Health Insurance
- See all


Don’t believe their ad saying they give more back to their customers THEY DON’T. HCF gave me $700 in extras which included dental cleaning. BUPA for… Read more
$8 a month more give me $650 minor dental ( not including dental cleaning ) and $650 MAJOR dental plus all the other stuff like optical. I recommend BUPA over HCF

Union Health
You can tailor your health insurance to what suits you and your family. Consultants are knowledgeable and helpful. Prices are better than other providers. Show details

HIF (Health Insurance Fund)
To What if ….. I appreciate Hif as a health fund but I am over companies who don’t notify you when they are changing their systems : after failing… Read more
to be able to use my card and paying in full , I have had two 30+ minute phone calls about not being able to update my app info and having to use a downloaded claim form that I submitted only to have to call again - as I was asked what I wanted to happen next …. Only to learn that my claim Had not landed despite getting the automated response … hoping a more direct. Email provided will help … going to Physio again ( great by the way) . Tomorrow … what would happen if I did not have funds to pay?? When I have just paid a years “ enrolment “ !! ….
- review of above : great response from consumer help but still unable to get app up and running after another hour on the phone and no capacity to know when sorted but card worked at Physio - But warning: no matter what they say initially if you have to receive a code on your phone finally as can’t use your phone to register you need TWO devices for task completion. However they say they’ll send me $100 gift card but it won’t get back practice I missed and cannot make up! And I’d prefer the latter! This kind of issue is going on at Telstras new security version. . Not the fault of the person I spoke to At Hif who halve to answer the call . They were always trying to help …

Please inform call staff about time frames

Health Care Insurance
Great service and easy to use insurance – Pretty happy with HCI. Easy to use app and always been easy to get through to them over the phone. Great service and they go out of their way to help you. Show details

St. Lukes Health
This non-profit health insurer offers generous cover, but has some notable drawbacks. Their fixation on Tasmanian wellness centres is irrelevant to… Read more
mainland customers. Seems to be for Tasmanian who are not fund members. Backend systems are slow and unreliable, with occasional outages. The UX is inconsistent and feels unpolished. Expect more call centre contact than you'd get with comparable providers, and tansaction processing times of 3–5 days that feel like a throwback to the era of batch processing. The app is third-party.

The software is a grab bag of forms that are printed out, the scanned via OCR. The design is… Read more

Latrobe Health Services
I have been a customer for over 12 years, I was on an old Gold Cover Policy, I called today, spoke with Kerry and she was absolutely fantastic. Great… Read more
Customer Service skills, very nice, helpful and professional. She found a cheaper Policy that fits my age & needs perfectly and save me $ 30 fortnightly. I was happy she provided me with the support I required and avoided me from moving to a different insurance company, she even offered to do a follow up with me in a week. I am delighted to have Kerry on the phone when I made the call, I definitely give Kerry a 5 stars.

Medibank Health Insurance
- See all


We were with Medibank for more than 30 years. They do not appreciate loyalty so I decided to switch providers. Finally, after a big circle and taking… Read more
advantage of free weeks offers, I came back to Medibank. They messed up my first claim and my second one was again lower than what it should have been. Their customer service had gotten worse. I went into Westfield Burwood branch and it was staffed by migrants who have not been trained well. They have not been educated about our local culture, that the first thing is to be courteous and make your customer feel welcomed. This middle aged woman did not even bother to look at my papers when I told her that I felt my rebate should have been more. I walked out feeling really disappointed and never again will I go back to Medibank once my free weeks are over. They deserve Zero stars.

Hi Kiy, thank you for taking the time to share your… Read more

Navy Health
I was recently diagnosed as pre-diabetic and high cholesterol and my doctor put me on a preventative drug regimen to try to address it before it… Read more
became a health issue. Navy health refused my claims even though I had not claimed any of my pharmaceutical benefit previously. Not only that they refused to respond to me personally even though both my husband and I are ex-navy and listed on the policy. Don’t bother with them you can get better service and more flexible premiums elsewhere.

Hi Sam, Thank you for your feedback. We're sorry to… Read more

NIB Health Insurance
- See all


Hm, recently got update email that the dental refund will change in Oct2026 if not using their cluster of dentists which are only 2500 Australia… Read more
wide. I had dodgy dentists before and am now in good hands. I want you NIB to still do the whole refund for a dental work code, no matter which dentist. It's far below the actual cost anyway.
Also the surprise that a covered private hospital was NOT including their lab work, was very unexpected additional cost. (Canberra Calvary Bruce hospital 2025) Lab work is usual during surgery pre and post. You cannot say when I check if NIB includes this hospital "yes", when the lab work is excluded which puts me another 720aud out of pocket ..
At least many hospitals are in the NIB network, and had no other surprises, but please state clearly if lab is not covered, as I would refuse daily lab parameters like full blood count when it is not life threatening necessary and no events.
Otherwise cover and claims were easy to process with NIB.
But am looking at other providers due to the lab out of pocket in covered hospital and dental refund changes.

Hi Sanja. Thank you for taking the time to provide your… Read more
RT Health Insurance 🏆 2026
4.9Award Winning, Affordable, Not-For-Profit Health Insurance.
Private health insurance in Australia
When you first take out private health insurance, you will need to decide if you require one or a combination of the following options:
If you don’t want any of them, you’re still covered for public hospital visits and basic checkups under Medicare, the Australian public healthcare system.
Getting private health insurance does not mean you give up your Medicare coverage; you can have both at the same time. Under Medicare, you can visit a public hospital as a public patient, but may be placed on a waitlist and cannot select your own doctor.
Medicare also covers your visit to a GP and most of the Medicare Benefits Schedule (MBS) fee for visiting a specialist, so if all you need are basic checkups, you may be fine relying on Medicare alone.
If you do decide to take up private health insurance, remember that you’re entitled to the same cover at the same price as anyone else, regardless of your risk profile. At the same time, if you're going to take out health insurance, it's important to choose a type that you actually use and aren't wasting money on. We go through the different types below.
Hospital cover
Private hospital cover is designed to take the strain off the public health system. To encourage people to join and spread the load across both systems, the government has several financial incentives for people to join a private health insurance fund.
If you’re interested in the financial benefits of private health insurance, or what rebates are available, you can read our article on the tax benefits of private health insurance.
Do I need hospital cover?
With hospital cover, you'll have peace of mind should any medical emergency or illness arise. You could otherwise be out of pocket for thousands of dollars or be put on a long waitlist for surgery.
Here are a few other reasons to take up private hospital cover:
- You get to choose your own doctor in either a private or public hospital.
- If you decide to go to a private hospital, you can choose from any that your provider has an agreement with.
- You have a higher chance of getting a private room when you go to a public hospital as a private patient.
- You may have reduced waiting times for some hospital procedures, such as elective surgery.
- Additional MBS fees and other costs may be covered as part of your policy.
- You can avoid paying the Medicare Levy Surcharge, which applies if you earn over $90,000 per year, or over $180,000 for families.
- You can avoid paying Lifetime Health Cover loading, which applies if you haven't taken hospital cover by the time you're 31.
If you have no problems admitting as a public patient to a public hospital should the need arise, then you may decide you don’t need private hospital cover. If the costs you incur during an unexpected hospital visit are less than the amount you would have spent on hospital cover up until that point, then you could finish out ahead without hospital insurance.
Unfortunately, there’s no way to tell if this will be the case, so many people take out hospital cover just for ‘peace of mind’, especially as they get older and the chances of needing it become more likely.
Here are some reasons to not get private hospital cover:
- Australia's public hospital system is generally good for those needing emergency surgery.
- The premium of your health insurance (which is what you pay for your policy) can be expensive, and unaffordable for many people.
- You may end up in a public hospital anyway for more complex medical conditions or treatments, as public hospitals usually have a wider range of medical equipment.
- You may pay more out of pocket for certain doctors, as private patients are often charged more than public patients, and your health insurance will probably only cover part of the cost.
Tiers of hospital cover
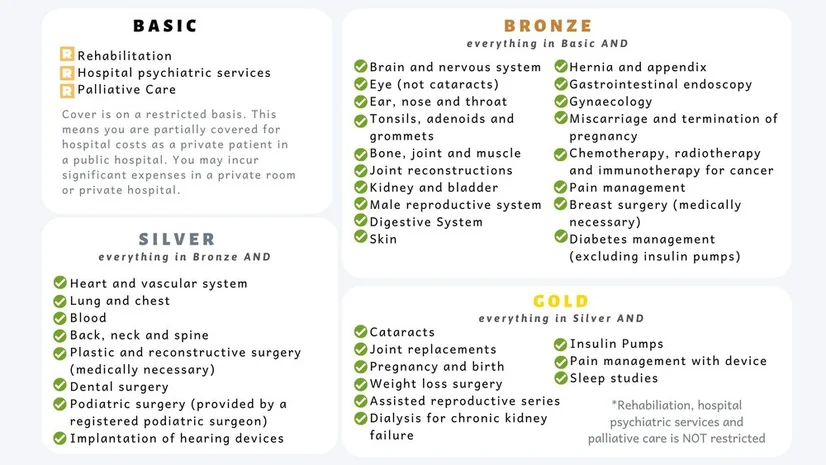
The tier system applies only to Hospital Cover and began rolling out in April 2019, becoming mandatory on April 1st 2020. It was designed to make comparison between providers more straightforward by dividing levels of cover into four tiers:
- Basic
- Bronze
- Silver
- Gold
Each of these tiers has its own minimum requirements that must be met in order for a policy to be classified as being part of that tier. These minimum requirements are cumulative, meaning that each increasing tier includes all the minimums of the tiers below it.
This graphic shows the minimal coverage requirements for each tier:
'Plus' policies
There is some wiggle room allowing providers to include additional coverage on top of the minimum requirements for a tier - these are referred to as ‘Plus’ policies. If an insurer offers a policy that provides cover that's above the minimum requirements of a tier, then they can advertise the policy as Basic Plus (+), Bronze Plus (+), or Silver Plus (+). Because a Gold policy covers everything, there’s nothing additional that can be added to it in order to make a ‘Plus’ version.
For example, surgery to remove wisdom teeth is covered under Dental Surgery, which is mandatory for Silver cover, but not Bronze. However, a provider may choose to include it on top of their normal Bronze policy to create a Bronze Plus policy.
This means you can claim this benefit without the full price increase that would come with an upgrade to Silver. This allows you to avoid paying for other mandatory benefits covered under Silver that you might never use, such as podiatric surgery.
It’s important to note that not all ‘Plus’ versions of the same tier are directly comparable, since each provider may choose to include different clinical categories as optional inclusions. For example, Provider A may offer a Bronze Plus package that includes bloodwork, while Provider B offers a Bronze Plus package that includes reconstructive surgery instead - they are both still Bronze Plus policies.
Extras cover
Extras insurance will help cover the cost of ancillary health needs, like dental care, clinical therapies and prescription glasses or contact lenses. If you don't use these services, you may prefer not to purchase Extras Cover as there is no tax benefit to having it.
If you're after just the basics and don't require more expensive treatments like orthodontics, you'll be able to extract the most value out of an entry-level policy. However, don't expect to get 100% back on your bills; most funds offer a 50-60% rebate.
Do I need extras cover?
There’s more value to be had from Extras Cover when you're using your extras regularly, so assessing your present and potential future needs is the best place to start.
Many providers won’t include extras cover for pre-existing conditions, so if you have a family history of a condition like osteoporosis or diabetes, you may need to be covered before these issues arise so that they’re not counted as a pre-existing condition.
Providers approach extras insurance in different ways. Some will give you a lot of flexibility over which services you want to include, while others have strict packages you must choose from.
If you start by writing down a list of your personal must-haves (e.g. complex dental, physiotherapy, and hearing aids) you can then whittle down the list of possible policies to only those that include exactly what you’re looking for.
If you're getting cover for your family or if you're aged between 55 to 79, then there are some perks to getting extras insurance:
- Families pay the same premium as couples, so children are covered for free. However, children under 5 on average typically get less than $100 in benefits each year, while children between 10 and $14 typically get almost $400.
- People aged 55 to 79 tend to get more use of extras insurance benefits than other age groups, and typically receive an average benefit of over $600 a year.
Dental cover
One of the most popular reasons to take out extras is dental cover. Dental is typically split into different levels of cover from routine or general up to major and complex procedures, with orthodontics usually being a separate option as well.
Additionally, depending on what procedures you have done and where, not everything may be covered under your Extras policy. For example, if you elect to have wisdom teeth taken out in a hospital, some of the hospital and doctor fees may not be covered under your Extras policy and you’ll have to pay these out-of-pocket.
Combined cover
Combined cover is hospital cover and extras cover combined in a single policy. Private hospital and extras insurance are different types of insurance, and you don't necessarily need both. Often, you can get a better deal by buying extras and hospital cover from two separate health funds.
Some people like the convenience of having to only deal with one health fund for both insurance types. Before you take out combined cover, think about whether you need both hospital and extras insurance.
Ambulance cover
Ambulance cover is the most basic type of cover, and covers the cost of an ambulance in an emergency.
Unless you live in Queensland or Tasmania, ambulance call-out fees are not covered under Medicare and will have to be paid for out-of-pocket. You can find out more about ambulance fees for your state in our ambulance cover article.
When shopping around, check with an insurer to see what kind of ambulance cover they offer. Some only offer ground transport in an emergency and will not offer air ambulance. Some might just cover emergency ambulance and exclude transport to transfer patients between hospitals.
What to consider when choosing health insurance
Once you've decided what level of cover is right for you, you can start comparing different providers and policies. Each policy will have a product disclosure stateent (PDS) - read these to understand the inclusions and exclusions.
Here are some more things to consider when choosing health insurance.
Your personal circumstances
What's going on in your life will usually have a significant impact on which type and level of cover will best suit you.
Consider the following questions:
- Do you have any pre-existing conditions that may require medical treatment in the near future?
- Are there any hereditary health conditions in your family that could have an impact on you?
- Are you planning on starting or growing a family and will you require obstetrics cover?
- Do you need cover for partners or dependants?
- How will your health needs and requirements change as you get older?
You should be honest about your health history when you take out a policy. Your insurer may not pay your claim if they believe that you have misled them.
Premiums
Generally, the higher your premium, the more benefits you can claim. You can usually tweak your health insurance policy to make your premium more affordable. Consider doing the following:
- Customise your excess. Choosing a higher excess (what you agree to pay towards a Hospital claim) will usually reduce your premiums.
- Choose a co-payment. This is a fee that you agree to pay for each day you're a patient in a hospital. It could be a more affordable option if your co-payment is less than what the excess would be and if you know how long you'll need to stay in hospital.
Waiting periods
Most health funds have a waiting period before you're able to claim on any services. The length of the waiting period usually depends on the type and complexity of the medical treatment.
- For hospital cover, waiting periods for pre-existing conditions or obstetrics (pregnancy) are usually 12 months.
- Waiting periods for extras vary; it can be 2 months for many services, and is usually 12 months for major dental treatment.
- Waiting periods typically won't apply if you're switching policies or health funds to a similar level of cover.
Decision time
One thing to remember that will help you avoid confusion when browsing policies is that hospital cover is sorted into Basic / Bronze / Silver / Gold tiers, while extras will be called whatever marketing name the provider has come up with for themselves (e.g. 'Lifestyle Extras,' 'Black Extras 60,' 'Essential Extras,' or 'Top Extras.')
It may be possible to mix-and-match your hospital and extras cover in many ways, such as combining the most expensive hospital cover with the most basic extras cover or vice-versa. Your provider may also offer some pre-selected hospital & extras combinations.
ProductReview.com.au is a great tool for seeing feedback about Health Insurance providers from real customers. You can browse our list of health insurance providers and easily see a summary of how other Australians rate their health fund for customer service, value for money, and transparency.
If you click through to an individual fund, you can use the Filter Reviews button to narrow down the reviews to see just those that are similar to you, or that you might be interested in reading.
Remember: insurance isn't forever. Reassess your policy regularly to ensure that it's meeting your needs and you're making the most of it.
This article is part of our series on private health insurance.
Disclaimer: The information on this website is for general information only. It should not be taken as constituting professional advice from the website owner - ProductReview.com.au. ProductReview.com.au is not a financial adviser. You should consider seeking independent legal, financial, taxation or other advice to check how the website information relates to your unique circumstances. ProductReview.com.au is not liable for any loss caused, whether due to negligence or otherwise arising from the use of, or reliance on, the information provided directly or indirectly, by use of this website.
Hi Simon, We're sorry to hear your concerns. We'd… Read more